Povej prijatelju o tem izdelku:
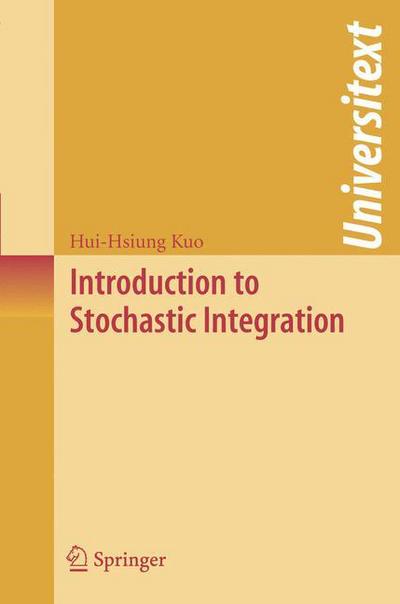
Introduction to Stochastic Integration - Universitext Hui-Hsiung Kuo
Cena
€ 67,49
Naročeno iz oddaljenega skladišča
Predvidena dobava 5. - 13. nov
 Božična darila lahko vrnete do 31. januarja

Prejemajte obvestila o novih izdajah izvajalca Hui-Hsiung Kuo
Kaj pravijo naše stranke:

Dodaj na svoj seznam želja iMusic
Introduction to Stochastic Integration - Universitext
Hui-Hsiung Kuo
It was the beginning of the Itˆ o calculus, the counterpart of the Leibniz–Newton calculus for random functions. The Itˆ o formula is the chain rule for the Itˆocalculus.Butitcannotbe expressed as in the Leibniz–Newton calculus in terms of derivatives, since a Brownian motion path is nowhere di?erentiable.
296 pages, 2 black & white illustrations, 2 black & white tables, biography
| Medij | Knjige Paperback Book (Knjiga z mehkimi platnicami in lepljenim hrbtom) |
| Izdano | 15. novembra 2005 |
| ISBN13 | 9780387287201 |
| Založniki | Springer-Verlag New York Inc. |
| Strani | 279 |
| Dimenzije | 156 × 235 × 18 mm · 476 g |
| Jezik | Angleščina |




