Povej prijatelju o tem izdelku:
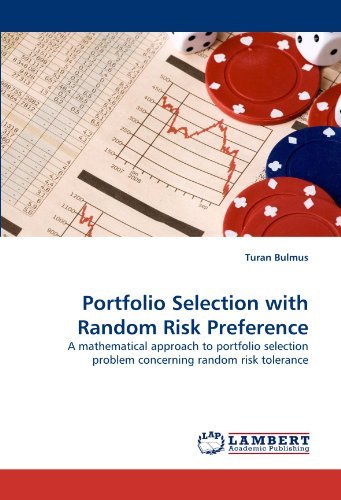
Portfolio Selection with Random Risk Preference: a Mathematical Approach to Portfolio Selection Problem Concerning Random Risk Tolerance Turan Bulmus
Naročeno iz oddaljenega skladišča
 Božična darila lahko vrnete do 31. januarja

Kaj pravijo naše stranke:

Portfolio Selection with Random Risk Preference: a Mathematical Approach to Portfolio Selection Problem Concerning Random Risk Tolerance
Turan Bulmus
In this study, I analyzed a single-period portfolio selection problem where the investor maximizes the expected utility of the terminal wealth. The utility function is exponential, but the Pratt-Arrow measure of absolute risk aversion or risk tolerance is random. This is due to the random variations in individual's decisions concerning stochastic choice. It is well- known that the investor is memoryless in wealth for exponential utility functions with a constant risk tolerance. In other words, the investment portfolio consisting of risky stocks does not depend on the level of wealth. However, it is shown that this is no longer true if risk tolerance is random. A number of interesting characterizations on the structure of the optimal policy are obtained
| Medij | Knjige Paperback Book (Knjiga z mehkimi platnicami in lepljenim hrbtom) |
| Izdano | 29. junija 2010 |
| ISBN13 | 9783838350851 |
| Založniki | LAP Lambert Academic Publishing |
| Strani | 72 |
| Dimenzije | 225 × 4 × 150 mm · 125 g |
| Jezik | Nemščina |
Ogled vseh Turan Bulmus